Efficient Least Squares For Estimating Total Effects Under Linearity And Causal Sufficiency
summary
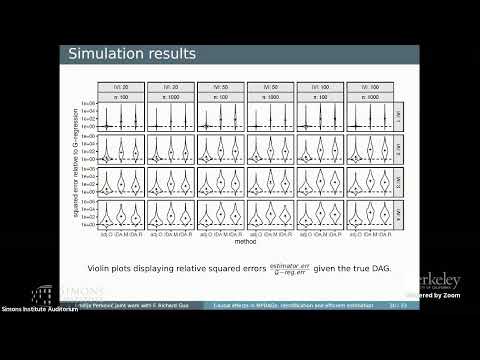
Proposes a reparameterization of linear SCMs over an MP-DAG into ordered bucket blocks and defines a plug‑in G regression estimator that estimates blockwise lambda matrices by least squares. Claims asymptotic dominance: any differentiable, covariance‑based consistent estimator has equal or larger asymptotic variance than G regression (Gaussian errors give MLE equivalence). Simulations show lower mean squared error than optimal adjustment, modified Cholesky and recursive regressions, and G regression still identifies some effects those methods cannot.
AI-written summary · about
chapters (10)
- 0:00Introduction
- 2:50Running Example
- 6:05Defining Causal Effects
- 14:42Causal Graph
- 16:07Previous Results
- 18:07Empty Deck
- 18:42Buckets
- 26:32G Formula
- 27:32Simulation
- 28:34Comparison
related talks
 28mSketching for M-Estimators: A Unified Approach to Robust Regression
 33mSimple Yet Efficient Estimators For Network Causal Inference...
 44mA Modern Maximum-Likelihood Theory for High-Dimensional Logistic Regression
 24mRandomized Least Squares Regression: Combining Model- and Algorithm-Induced Uncertainties
 49mSo you think you know about linear regression ...
 44mInvariance, Causality and Novel Robustness
 45mThe Statistical Fairness-Accuracy Frontier
 01h 01mRobustness, Stochastics, Uncertainty 2