Payments for the 21st century and beyond

summary
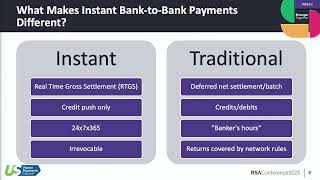
A new US real-time rail provides immediate, final settlement between banks with built-in messaging for invoices and requests; RTP launched November 2017 and already has over 150 financial institutions connected, adding ~50 per quarter so about 61% of US deposits can receive RTP today and target ~75–80% this year. Messages use iso 2022 formats, support request-for-payment flows, carry rich remittance, and a document service (90-day TTL) lets senders append PDFs or XML for AI-driven straight‑through processing.
AI-written summary · about
chapters (26)
- 0:00Introduction
- 0:50What is the clearinghouse
- 2:27Why the ecosystem is broken
- 3:37History of payments
- 6:48Immediateness
- 8:17Artificial Intelligence
- 9:02Natural Language Processing
- 9:36Payments rails
- 11:22Changing needs of customers
- 14:53Realtime payments
- 18:35Other payment systems
- 19:01RTP adoption
- 20:12How does RTP differentiate from other platforms
- 21:02How does RTP innovate
- 24:02Use cases
- 24:41RTP brand promise
- 26:51Request for payment
- 27:42Rich data features
- 28:09B2B life cycle
- 29:34Document services
- 31:30How it works
- 32:28What do these things have in common
- 32:46New business models
- 33:28Seamless integration
- 34:18Consolidation in the industry
- 38:33Fraud
related talks
 40mWhat are Faster Payments and Why Should a Security Practitioner Care?
 52mThe Critical Importance of Identity for Instant Payments
 26mMastering API Platforms for Enhanced Payment Integration
 27mDriving revenue opportunities across the Open Banking ecosystem
 35mHow FinTech is powering future payments
 59mPayments
 48mPayments: The Next Frontier
 15mThe Next Payments Frontier